What does “subject to” mean when selling a house in Georgia?
Selling a house “subject to” means transferring ownership (the deed) to a buyer while the existing mortgage stays in the seller’s name — the buyer simply takes over the payments instead of getting a new loan or paying off the balance. It’s legal in Georgia, but it carries real risk for the seller: most mortgages include a due-on-sale clause that technically allows the lender to demand full repayment upon transfer, and the loan remains the seller’s legal and credit responsibility if the buyer stops paying. A straightforward cash sale avoids this risk entirely by paying off your mortgage in full at closing.
⚠️ This page provides general information, not legal or financial advice. Subject-to transactions carry lending, credit, and tax implications — always consult a Georgia real estate attorney and a financial advisor before pursuing one.
How our cash offer process works
- Tell Us About The Property — Fill out our short form or call directly. We'll gather quick details about your home and your mortgage situation.
- We Visit, In Person — A local team member schedules a brief walkthrough. No strangers trampling through your home — just a respectful, quick visit.
- Receive A Written Offer — A fair, written cash offer with no hidden fees. Take your time — there's no pressure to accept.
- Close On Your Timeline — Choose your closing date. We can close in as little as 7 days, and your mortgage is paid off in full at closing — no lingering liability on your credit.
Understanding subject to sales in Georgia.
A subject to sale is a creative financing arrangement, most often used by real estate investors, where:
- Title transfers to the buyer, but the existing mortgage loan stays in the seller’s name — the buyer isn’t formally assumed onto the loan by the lender.
- The buyer makes the monthly payments directly, or through a servicing arrangement, instead of getting new financing.
- The seller remains legally and financially responsible for the loan in the eyes of the lender, even though they no longer own the property.
- Most mortgages include a due-on-sale clause, which technically gives the lender the right to demand full repayment when the property is transferred, under the Garn-St. Germain Depository Institutions Act of 1982.
Why subject to sales aren't risk-free for sellers.
- Your credit stays on the line. If the buyer misses payments, it's your credit score that takes the hit — not theirs — since the loan is still legally yours.
- The due-on-sale clause is a real (if rarely used) risk. Lenders can call the loan due upon transfer. In practice, they often don’t if the loan is performing and near market rate, since foreclosing costs the lender money — but “rarely enforced” isn’t the same as “never enforced,” especially if interest rates or bank policy shift.
- You have limited control once the deed transfers. You're relying on the buyer to maintain the property, insurance, and payments responsibly for as long as the arrangement lasts.
- Georgia's foreclosure process is fast. Georgia is a non-judicial foreclosure state, and the process can move in as little as 60 days from a missed payment to a courthouse sale — if the buyer stops paying, there's very little time to react before it affects your credit and potentially the deed you signed away.
Why many sellers choose a straightforward cash sale instead.
- Your mortgage is paid off completely at closing — no ongoing liability, no credit risk, no due-on-sale exposure.
- You walk away with certainty, not a multi-year arrangement dependent on someone else's payment history.
- No waiting to see if the buyer performs — the transaction is complete the day it closes.
- We handle the payoff coordination directly with your lender, so there’s nothing left hanging once you sign.
What sellers say about working with us
Rated 5.0 across 97 Google reviews.
The team at Assured Property Solutions Columbus is fully dedicated to providing an exceptional experience. Their communication was clear and consistent, and the transaction was seamless from beginning to end.
— The Blumen Group, Google Review
Jacob is a great resource to have and a wealth of experience. Smooth transaction process and easy to work with. Highly recommend.
— Jackson K, Google Review
I have worked with Jacob on several deals and each one he has been a pleasure to work with. He always answers the phone to help me with any of my concerns. Jacob is the most trustworthy person I have dealt with in this profession.
— Alex Lawson, Google Review
Understanding Georgia's mortgage transfer and foreclosure rules.
| Factor | What Georgia/Federal Law Says |
|---|---|
| Governing Law on Due-on-Sale | Garn-St. Germain Depository Institutions Act of 1982 (federal) |
| Is Subject To Legal? | Yes — it's not illegal, but it creates civil (not criminal) risk if the lender enforces the due-on-sale clause |
| Lender Enforcement in Practice | Uncommon on performing, near-market-rate loans, but not guaranteed — rate environment and lender policy can change this |
| Georgia Foreclosure Type | Non-judicial — governed by O.C.G.A. § 44-14-160 et seq. |
| Typical Foreclosure Timeline | As fast as 60 days from first missed payment to courthouse sale |
| Right of Redemption After Sale | None — Georgia provides no statutory right of redemption once the sale is complete |
| Required Notice Before Sale | 30-day written notice via certified mail (O.C.G.A. § 44-14-162.2), plus 4 weeks of public advertisement |
Sourced from the Garn-St. Germain Act (12 U.S.C. § 1701j-3), O.C.G.A. § 44-14-160 et seq., and published Georgia foreclosure law resources, 2025–2026.
What this means if you’re considering subject to or facing payment trouble:
- Georgia’s foreclosure speed cuts both ways. It’s part of why some sellers consider subject to arrangements to avoid foreclosure — but it’s also why a buyer’s missed payment can escalate quickly if you’re still legally on the loan.
- There’s no redemption period after a Georgia foreclosure sale, meaning timing matters enormously if you’re relying on someone else’s payments.
- A full cash payoff removes this risk entirely — once your mortgage is paid off at closing, Georgia’s foreclosure timeline and due-on-sale rules simply no longer apply to you.
Not a national iBuyer. Not a lead-generation site. A local team that's straightforward about the risks.
- We're a family-owned, Columbus-based company — you'll talk to the same local people from your first call through closing.
- We buy with our own funds, not creative financing, so your mortgage is paid off completely, not taken over.
- We give you a real, written offer, not an automated estimate that changes later.
- We'll tell you honestly if a straightforward cash sale is a better fit for your situation than a subject to arrangement — even if that means a different conversation than you expected.
- 97 Google reviews at a 5.0 rating — verify our track record before you ever pick up the phone.
Clear Terms. No Surprises.
- No commissionsDeal directly with us, no 6% agent cut.
- No repairsSell as-is, nothing to fix or clean.
- No staging or showingsOne private walkthrough, then an offer.
- No closing feesWe cover standard closing costs.
THREE OFFER GUARANTEE: We know Georgia — and we're here to help.
We're a small, local team. When you call, you'll reach someone who actually understands mortgage payoffs, subject to risk, and the Georgia market — not a call center.
Subject To VS. Full Cash Payoff
| Item | 📋 Subject To Sale | ✅ Full Cash Offer — Assured Property Solutions |
|---|---|---|
| Mortgage Status | Stays in your name, buyer makes payments | Fully paid off at closing |
| Credit Risk | Yours, if the buyer defaults | None — loan is closed out |
| Due-on-Sale Exposure | Yes, technically enforceable | None — no transfer subject to an existing loan |
| Certainty | Depends on buyer's ongoing performance | Complete the day you close |
| Closing Timeline | Varies by arrangement | As fast as 7 days |
| Commissions | Often none, but ongoing risk instead | None — $0 |
| Closing Costs | Varies by agreement | We cover them |
Situations we help with
- Behind on Payments: Often can help you avoid foreclosure entirely.
- Upside-Down Mortgage: Often structure short-sale-friendly offers with your lender.
- Foreclosure: Stop the process before it costs you equity.
- Divorce: Sell quickly and split proceeds cleanly.
- Inherited / Probate: We handle probate paperwork directly.
- Tired Landlord: Sell the rental as-is, tenants and all.
- Vacant Property: Stop paying to maintain and insure an empty house.
Helpful resources
- Consumer Financial Protection Bureau (mortgage servicing and due-on-sale information)
- Georgia Mortgage Assistance Program (hardship-related payment help)
- State Bar of Georgia Lawyer Referral Service
- HUD-Approved Housing Counseling Agencies (free, independent guidance on foreclosure alternatives)
- Your mortgage servicer's loss mitigation department
Local across the Columbus, GA region.
We're based in Columbus and buy houses throughout the surrounding area, including:
- Columbus, GA
- Midland, GA
- Fortson, GA
- Phenix City, AL
- Smiths Station, AL
- Opelika, AL
- Fort Mitchell, AL
- Muscogee & Harris Counties
Questions about selling a house subject-to in Georgia
Local, family-owned
The person on this page is the person who answers the phone.
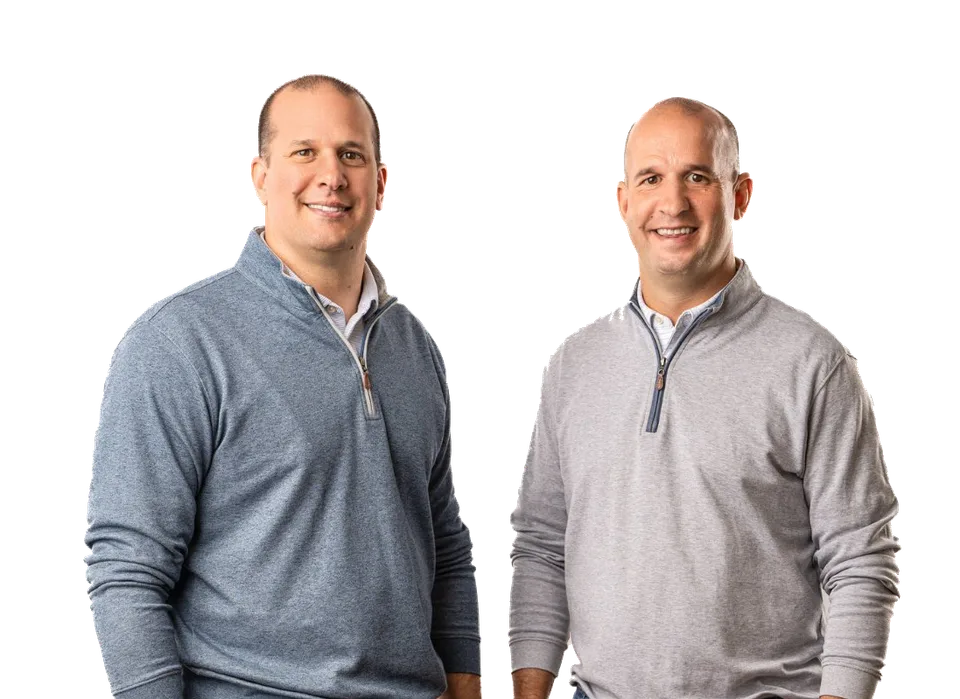
Preston Letts & Andrew Letts
Owners of Sell Now Columbus and Assured Property Solutions. Family-owned in Columbus since 2017. Call and you reach someone who can actually make a decision.
(706) 670-6420As-is, any condition
No repairs, cleaning, or staging before closing.
Offer in 24 hours
A written, no-obligation number usually within a day.
Close in 7 days
Or later — you choose the closing date.